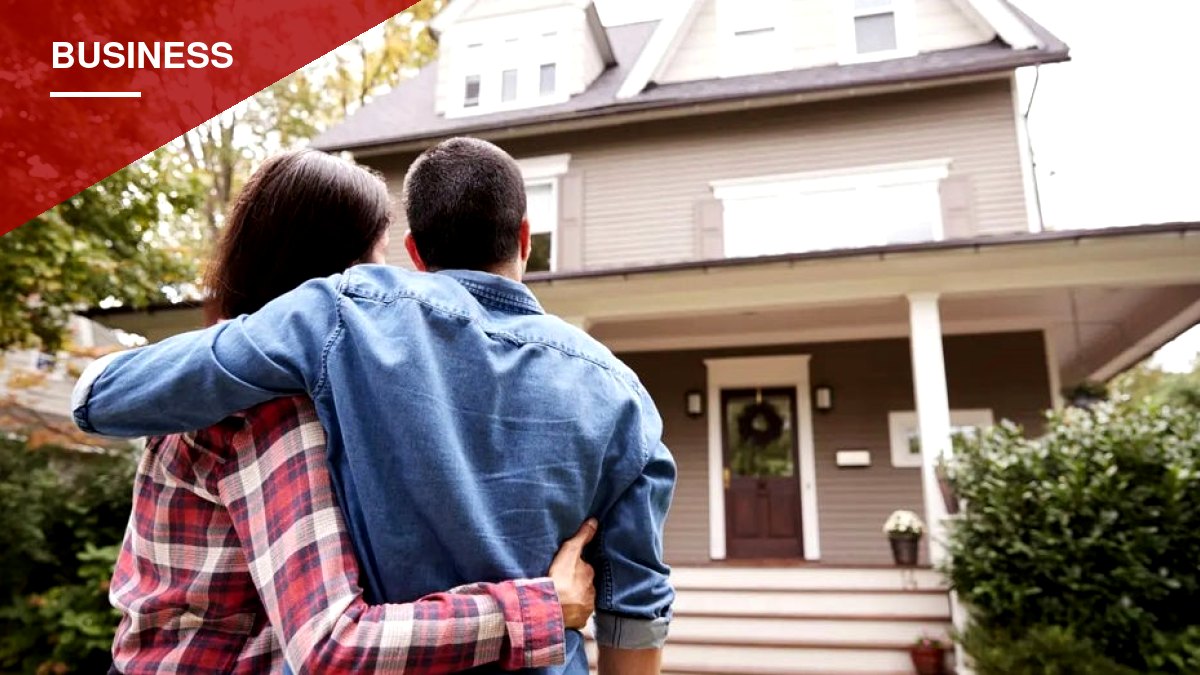

Comparing today’s mortgage rates to the 14% rates of the 1980s misses a key part of the affordability story, according to an analysis by financial commentator Ted Jenkin: home prices have grown far faster than incomes, making the overall cost of buying a house much steeper than a simple interest-rate comparison suggests.
In 1984, the median new home sold for about $79,900 while median household income was roughly $22,400 — a home-price-to-income ratio of about 3.6 times income. The average 30-year mortgage rate that year was 13.9%.
By 1990, that ratio had climbed to about 4.1 times income, with the median new home costing $122,900. In 2000, the ratio held near 4 times income even as mortgage rates stayed above 8%. By 2010, the median new home cost roughly 4.5 times median household income. By 2020, it was approaching 5 times income, with homes at $330,900 against household income of roughly $68,000.
As of August 2026, the median existing home price stood at $429,100, against a median household income of $87,460 for 2025 — about 4.9 times income. The average 30-year mortgage rate hit 7.40% on Oct. 8.
The down payment gap
The analysis points to the down payment as a particularly overlooked burden. A 20% down payment on the $79,900 home in 1984 came to about $16,000, or roughly 71% of that year’s median household income. Today, 20% down on a $429,100 home is nearly $86,000 — about 98% of median household income, before closing costs, moving expenses or furniture.
Borrowing the remaining $343,000 at 7.28% produces a principal-and-interest payment of roughly $2,350 a month, before property taxes, homeowners’ insurance, HOA fees and maintenance are added in.
Orange County’s affordability squeeze
The pressure is especially visible in Orange County, California, where state officials have classified a $104,200 salary as “low-income” given local housing costs — an example cited as evidence of how far home prices have outpaced what counts as a comfortable income in high-cost regions.
Taken together, the analysis argues that today’s buyers are squeezed from several directions simultaneously: home prices relative to income, the cash required for a down payment, and the cost of borrowing once a mortgage is secured. That combination, rather than the interest rate alone, is what separates the current housing market from the one previous generations navigated.


You must be logged in to post a comment Login