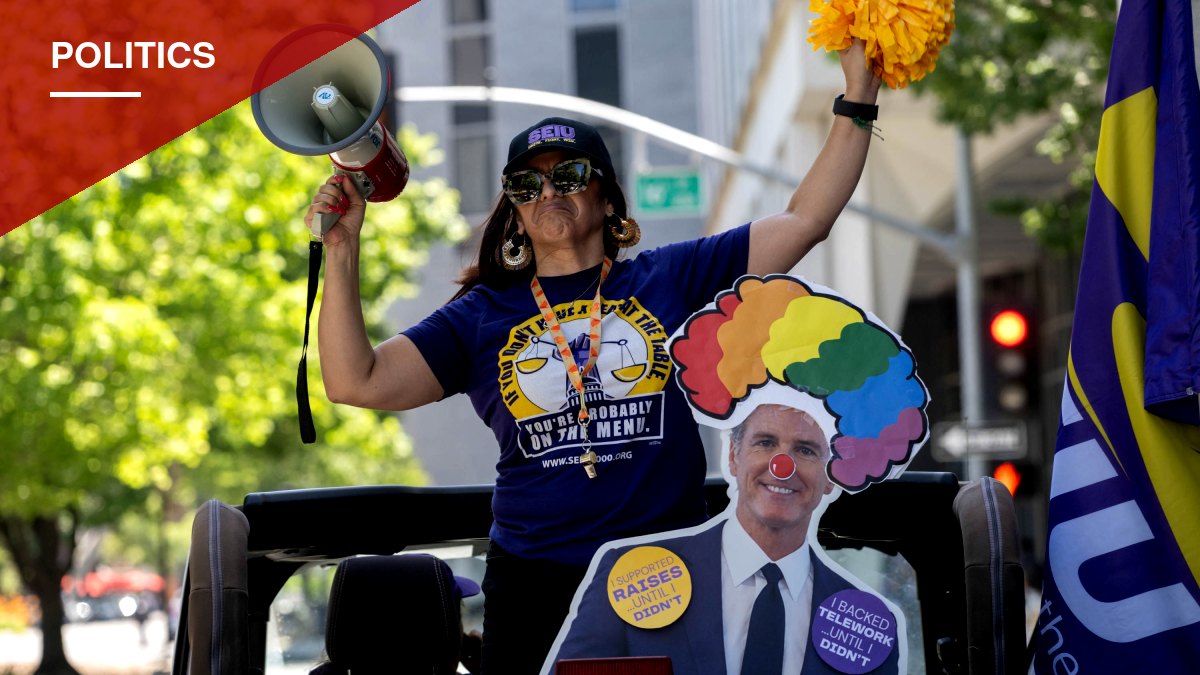

California’s largest public pension system, CalPERS, is short $153 billion of what it needs to cover benefits it has promised current and future retirees, even as more than 63,000 retirees collect six-figure annual pensions. One retired government employee took in nearly half a million dollars in pension payments last year, according to a California Post review.
The gap matters well beyond Sacramento. Orange County residents, like taxpayers across the state, help fund public pension systems through local and state taxes, and shortfalls in those systems ultimately become public budget problems — meaning less money available for police, fire, libraries and road repairs.
The roots of the shortfall trace back to 1999, when then-Gov. Gray Davis signed Senate Bill 400, expanding retirement benefits for state employees. Local governments, including many in Southern California, followed with their own enhanced benefit packages. Those benefits were applied retroactively, increasing compensation for work employees had already performed, on the assumption that strong investment returns would cover the added cost without burdening taxpayers.
When markets later crashed, the enhanced promises weren’t rolled back. Taxpayers absorbed the difference, and public agencies have been managing the fallout ever since.
A local vantage point
Jon Fleischman, a longtime California political strategist who previously handled media relations for the Orange County Sheriff’s Department, has described watching able-bodied deputies retire at 50 and then take jobs with other law enforcement agencies or private security firms — collecting both a pension and a new paycheck. Those retirees were simply following rules state and local leaders had put in place, he said.
Fleischman argues that practices like pension spiking and


You must be logged in to post a comment Login