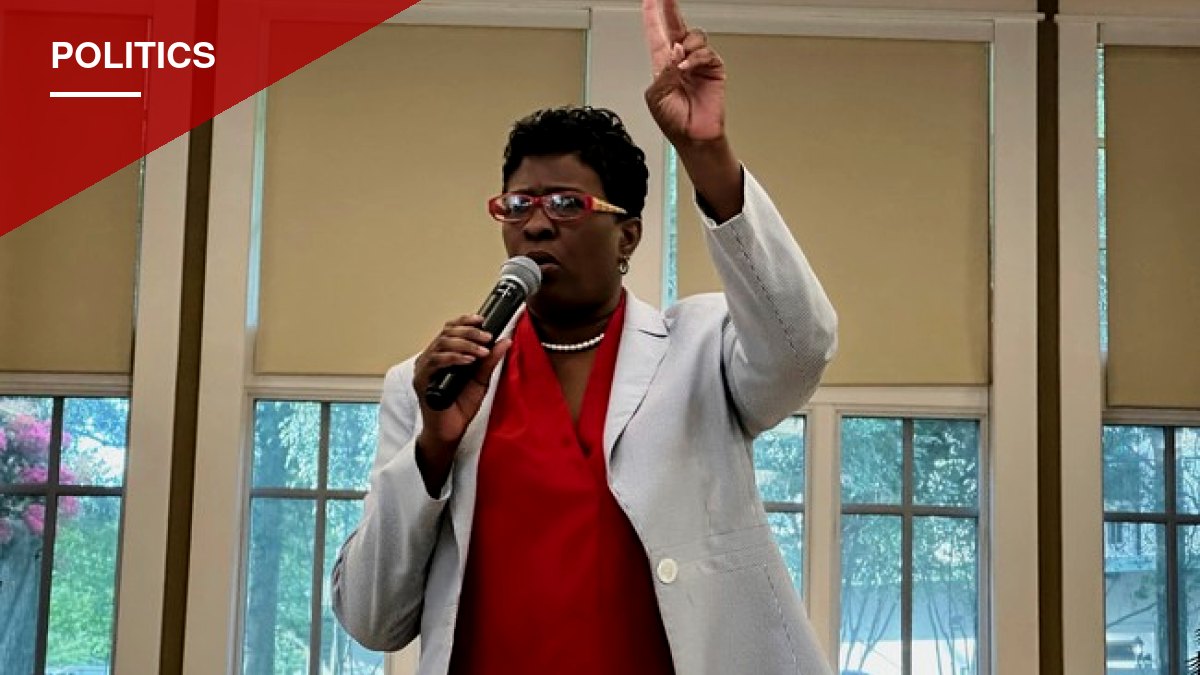

Georgia Insurance and Fire Safety Commissioner-elect Keisha Sean Waites has outlined a 100-day agenda that includes a proposal to bar insurers from using credit scores and ZIP codes when calculating auto and homeowners insurance premiums.
Waites, a Democrat and former Atlanta city councilwoman and state representative, defeated Republican incumbent John King in last week’s election. She takes office alongside Senator John Ossoff, who was reelected, and Governor-elect Keisha Lance Bottoms, the former Atlanta mayor.
In a post-election interview, Waites said credit scores and ZIP codes should not factor into how insurers price risk. “Those things have nothing to do with calculating your risk as it relates to your insurance premiums,” she said.
Her agenda lists two other priorities: strengthening consumers’ ability to recover money or take legal action against insurers in cases of alleged wrongdoing or negligence, and streamlining Georgia’s insurance regulatory process to attract more companies and increase competition in the state.
Pushback on the credit and ZIP code proposal
The plan to eliminate credit scores and ZIP codes from premium calculations has drawn criticism from people who argue it would raise costs for lower-risk policyholders rather than lowering overall insurance costs.
Critics note that in Georgia, a driver with excellent credit currently pays about $1,300 a year for full coverage, while a driver with poor credit pays about $3,139 — a difference of roughly $1,839. That gap, they argue, is larger than the typical price difference seen across most ZIP codes in the state.
The argument against the ban holds that insurers still need to collect enough in premiums to cover the same total volume of claims. If credit scores and ZIP codes are removed as rating factors, the cost would shift to other variables, meaning policyholders with strong credit in lower-risk areas would likely lose existing discounts while those with poor credit or in higher-claim areas would see lower rates.
Opponents of the proposal point to Washington State, where a temporary ban on credit-based insurance scoring was followed by premium increases for more than 60% of drivers, as previous discounts were spread across the broader pool of policyholders.
A narrower path through the legislature
Any changes Waites wants to make would require cooperation from the Georgia General Assembly. While Democrats flipped the state House in this election cycle, Republicans retained control of the state Senate by a narrow margin, meaning the fate of her proposals will depend heavily on how Senate Republicans respond.


You must be logged in to post a comment Login